

Over the past four days, People's Daily (Renmin Ribao), a flagship newspaper of the Communist Party of China (CPC), has run four articles under the byline "Zhong Caiwen(钟才文)," a pen name that is widely seen to speak for the Party's top economic decision-makers.
The series moves from stock-taking to a to-do list: the first article argues the economy's resilience, the second makes China's case to the world, the third explains what the 4.7 percent economic growth rate China achieved in H1 really means, and the fourth turns to the work plan for the rest of the year, fleshing out a meeting of the Political Bureau of the CPC Central Committee held on July 30 that set the agenda for the second half.
Read together, the articles make four key arguments: that the 4.7-percent growth is the number within expectations, not a disappointment; the structural upgrade behind it is genuine; major risks are being addressed deliberately; and China remains an anchor for the world economy. In addition, the fourth article details exactly how the rest of 2026 will be managed.
4.7 PERCENT: WITHIN TARGET RANGE
On China's economic performance in H1, one of the articles presents analysis in three layers.
First, it is on target. The 4.7-percent growth rate sits inside the 4.5-5 percent target range set at the Central Economic Work Conference, held last December, and the "two sessions" in March this year, a pace in line with potential growth. The economic performance aligns with the CPC leadership's scientific assessment of the economic situation and its strategic deployments, laying a solid foundation for a strong start to the 15th Five-Year Plan (2026-2030).
Second, the quality of growth. New growth drivers contributed more than 40 percent of growth directly. AI-related patent grants rose 34.8 percent year on year. Clean energy accounted for 36.2 percent of power generation by industrial enterprises above the designated size. The retail penetration rate of new energy vehicles reached 54.1 percent. Lithium battery output was up 39.3 percent. Per capita disposable income rose 5.2 percent in nominal terms, and service retail sales, 5.3 percent.
Third, the resilience of the economy. The articles credit early preparations (building new-energy systems and strategic oil reserves before the Middle East crisis, diversifying export markets) for keeping fuel supplies normal while many countries faced shortages and spiking prices. One number deserves particular attention: profits of industrial enterprises above the designated size rose 18.7 percent in H1, nearly four times faster than GDP. That is the crux of the CPC's message that speed alone, or any single quarter's data, is the wrong yardstick: watch profits, jobs, prices and structure instead. Notably, the articles also concede that demand is still weaker than supply and that investment is under pressure to stabilize.
UPGRADE AND DE-RISKING
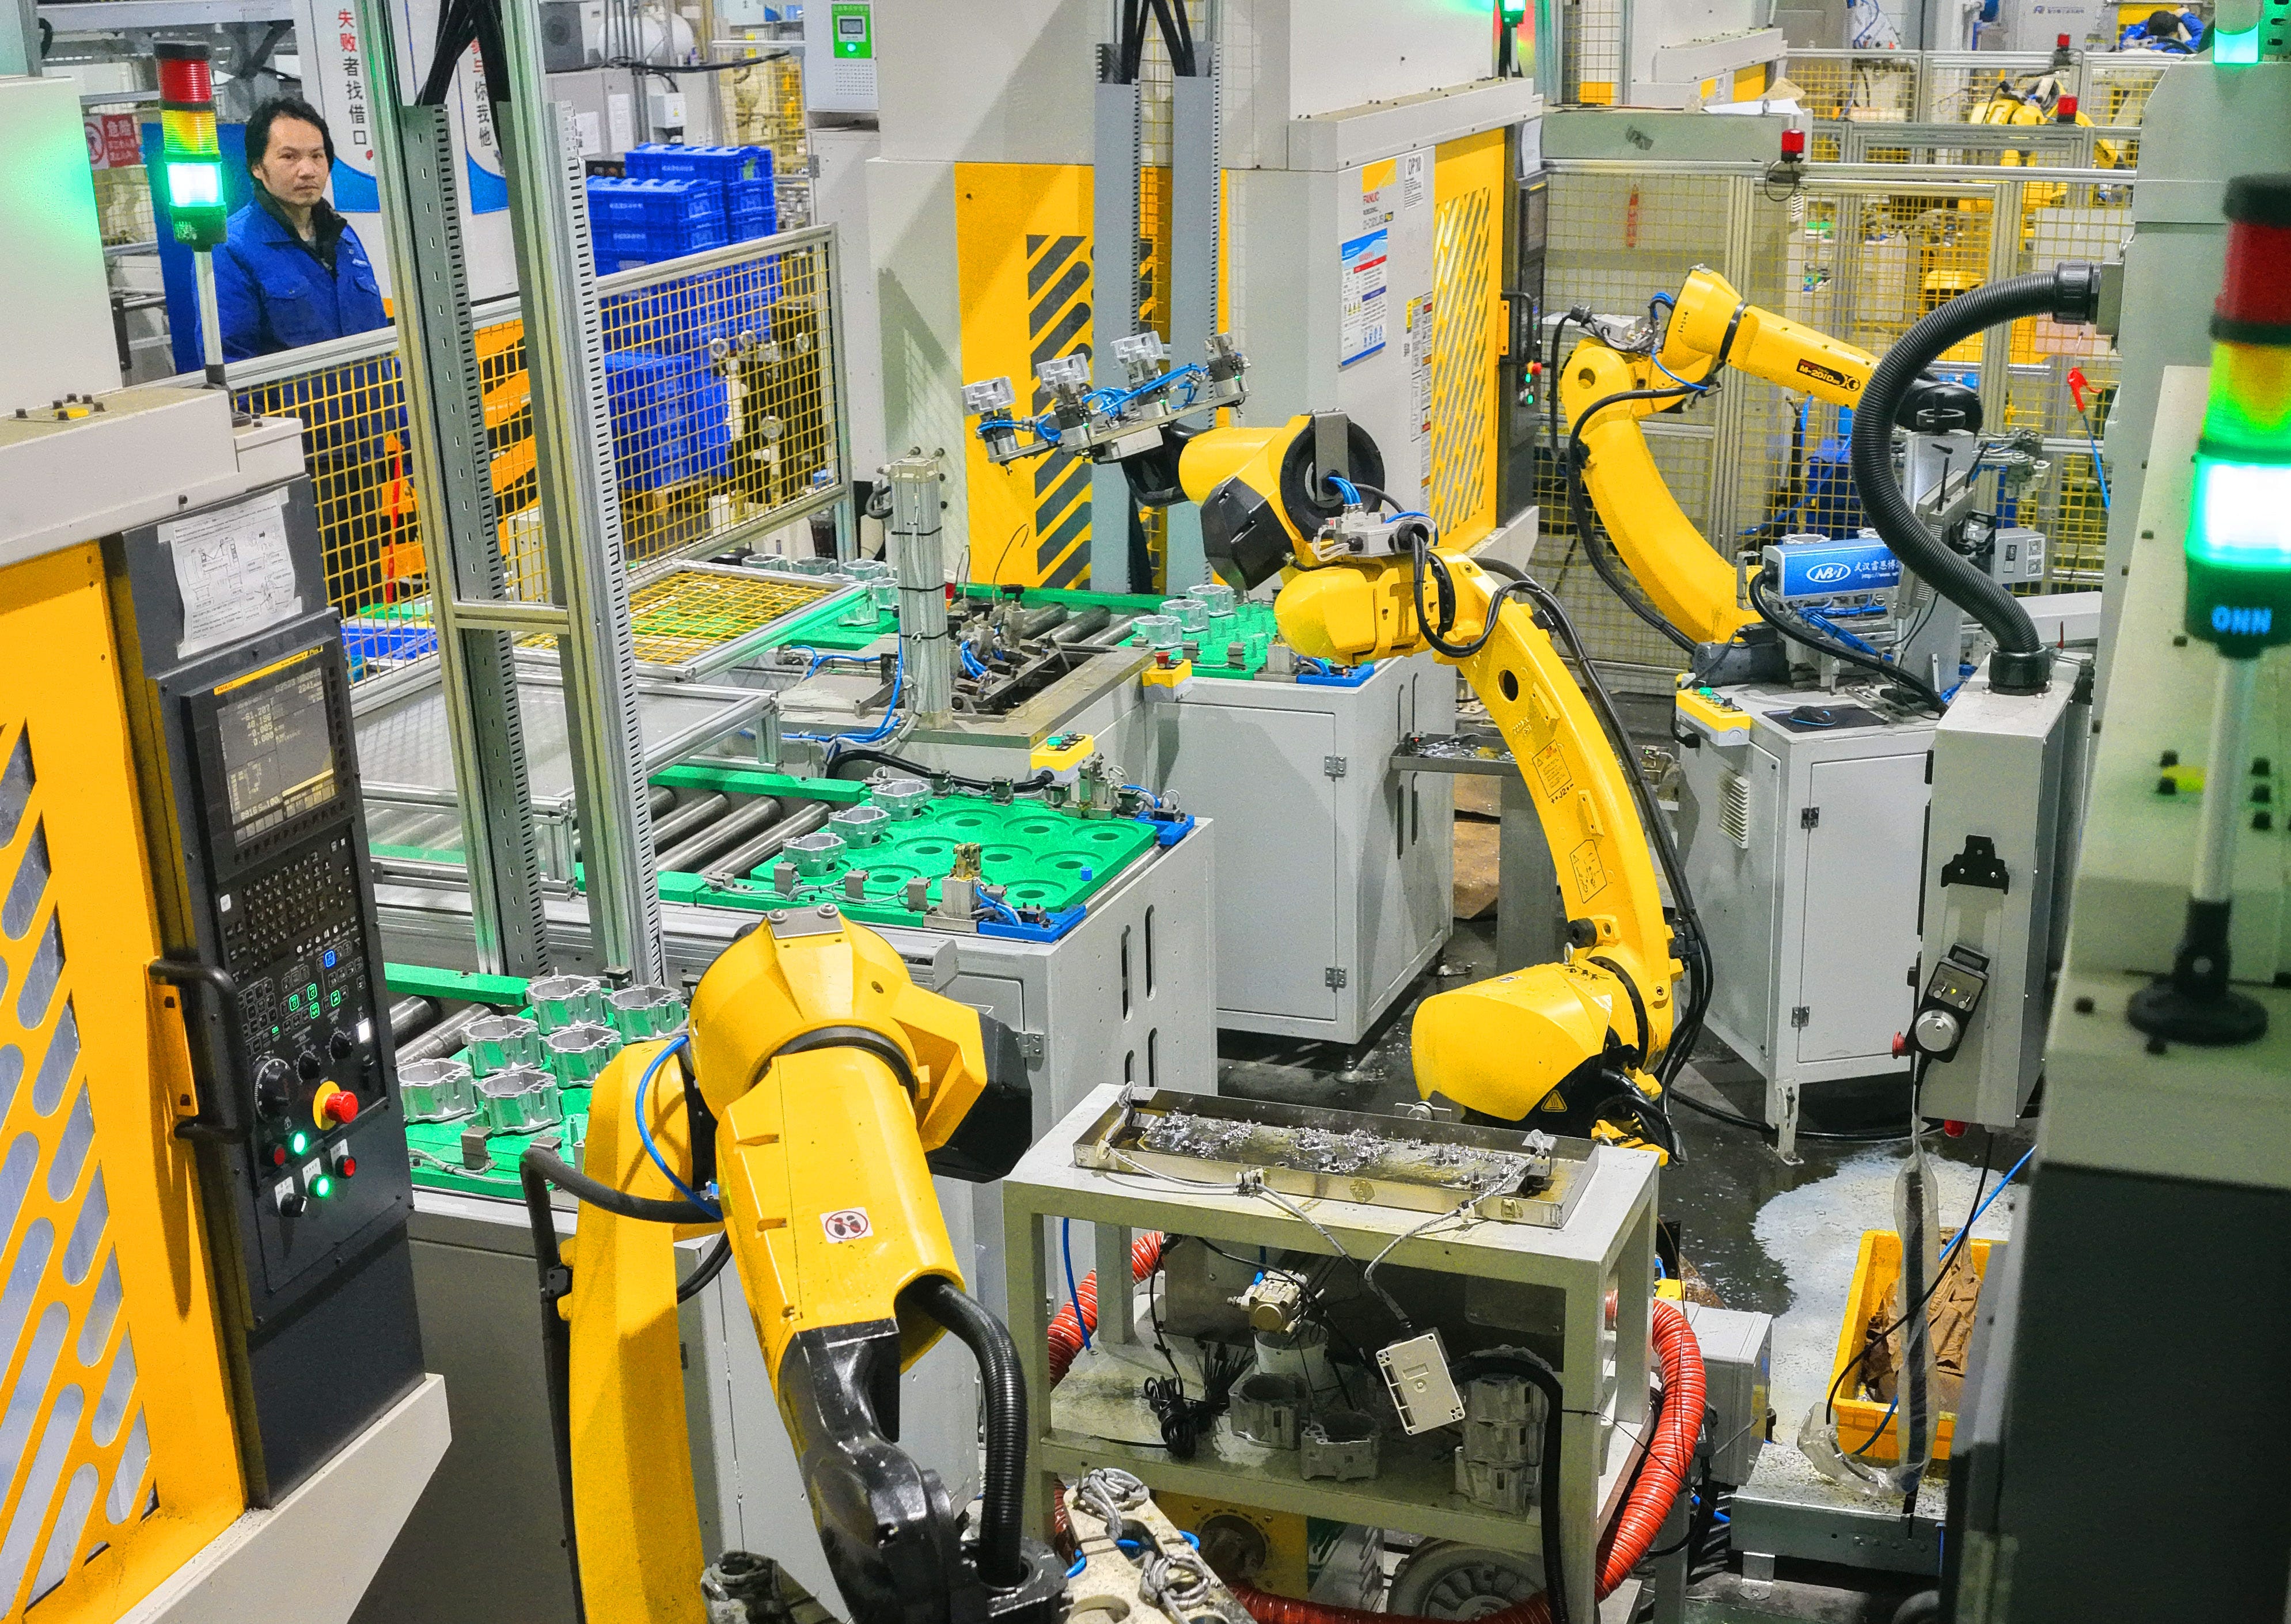
The "structural upgrade" story is tangible. A new-energy vehicle plant in the Yangtze River Delta can assemble 10,000-plus components within four hours, and a humanoid robot in the Pearl River Delta draws on a "one-hour industrial ecosystem." China's global innovation index ranking has risen from 34th in 2012 to 10th in 2025, with the world's largest number of top-100 sci-tech clusters for three straight years. Eight of every 10 humanoid and quadruped robots sold worldwide in H1 were made in China, and outbound licensing deals for Chinese innovative drugs totaled about $110 billion. This year, rockets were recovered both at sea and on land, and a 3-trillion-parameter open-source model (Kimi K3) was released. Green power now accounts for nearly 40 percent of national electricity use. Over the past decade, global average costs for wind and solar power have decreased by more than 60 percent and 80 percent, respectively.
The point of these specifics is that China’s growth story has shifted: from speed to substance, from quantity to quality, and from imitation to original innovation.
The series is equally candid about the three risk files China has been managing for years. Property markets are bottoming out: in some first- and second-tier cities, second-hand home sales now exceed new-home transactions. Hidden local government debts are being replaced in an orderly way, and the number of financing platforms keeps shrinking. High-risk small and mid-sized financial institutions are being resolved and consolidated, and the articles insist the bottom line, no systemic risk, has been maintained.
The third article (上半年经济增长4.7%说明了什么?) points out resolving these problems "has a contractionary effect on the economy, and some growth cost must be paid." The message to the world is that the leadership has accepted short-term pain as the price of long-term stability, and that the choice was deliberate, not accidental. The fourth article then spells out the paths: debt resolution through the package of swap measures, property stabilization through high-quality urban renewal, and financial risk control through shrinking and reforming small local banks.
CHINA, STILL THE WORLD'S ANCHOR
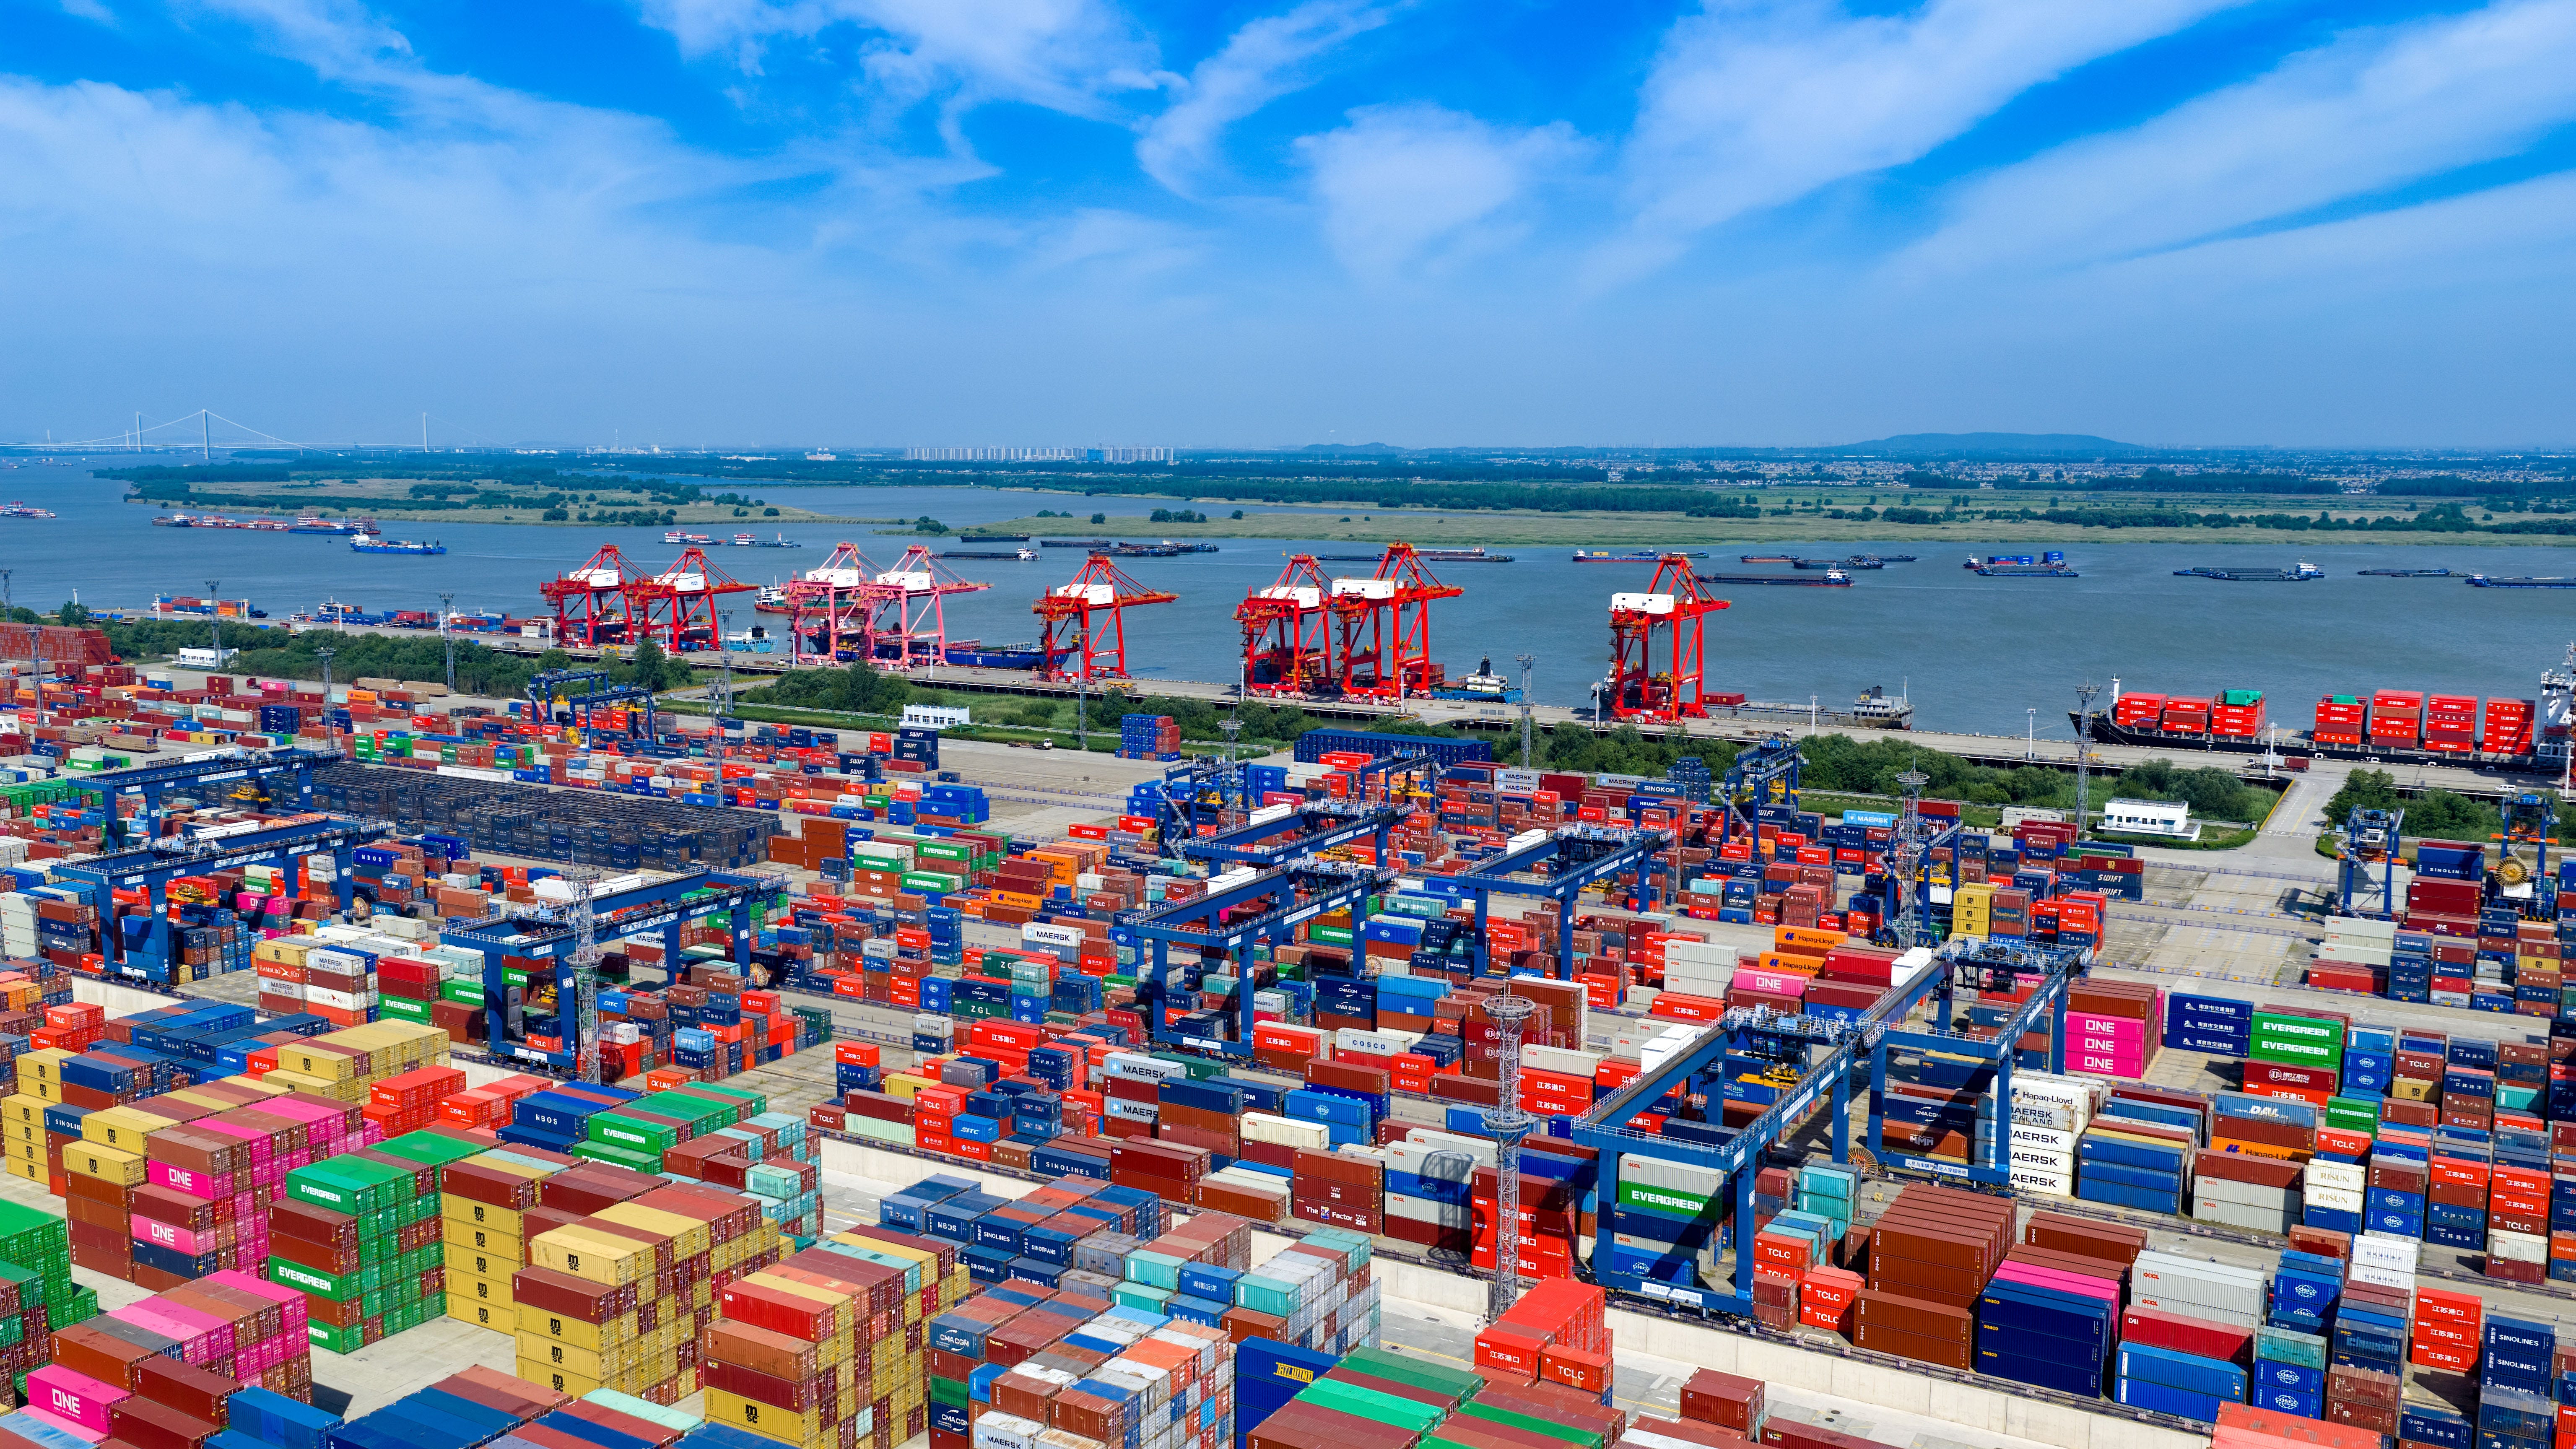
The second article makes the outward-facing case: China has contributed roughly 30 percent of global growth for years, and domestic demand now drives over 80 percent of its own growth, with consumption close to half. It notes that during the Hormuz Strait disruption this spring, China -- relying on a nearly 40 percent share of green power in its electricity mix -- reduced oil imports yet kept factories running. The Wall Street Journal reported that China propped up the world economy by importing less oil, while Le Figaro argued this was the second time China had rescued the global economy since 2008.
The series also fires back at the "China Shock 2.0" narrative with numbers: China imports more than 20 trillion yuan (about $2.95 trillion) a year and is the top export destination for nearly 80 countries; since May 1, it has extended zero-tariff treatment to all 53 African countries with diplomatic ties. There is also the "cool power" anecdote (Chinese air conditioners flying off shelves during Europe's heatwave), which reflects how made-in-China products benefit world consumers by efficiently and agilely responding to overseas market demand.
ROADMAP FOR H2
The fourth article, titled "Steadily advancing high-quality development," (推动高质量发展行稳致远) walks through decisions made at the July 30 meeting for the rest of the year, and the detail matters. On fiscal policy, the article notes that average daily treasury balances ran high in H1, a hint that firepower is ample; spending will be accelerated, and 800 billion yuan in a new policy-oriented financial instrument has been set aside, mainly to replenish capital for major projects. On investment, it concedes that fixed-asset investment fell 5.7 percent in H1, and prescribes a familiar medicine: speed up the "six networks" infrastructure program and push approvals of major 15th Five-Year Plan projects during the third-quarter construction season.
On the policy stance itself, the articles address the question markets care about most: whether the response is big enough.
The public debate has narrowed into a simple equation, in which any slowdown is blamed on insufficient stimulus and any fix is measured in trillions of yuan or percentage points, Dong Yu, executive deputy director of the Institute for China Development Planning at Tsinghua University, writes in a China News Service analysis published Tuesday.
That, he argues, underestimates macro management. The policy makers' answer, stated bluntly in the articles, is that it will not follow the path of heavy stimulus as some high-debt, high-deficit economies do; aggregate policy stays proactive, structural tools aim precisely, and the goal is to avoid policy dependence. Incremental measures will still come when circumstances call for them, the articles promise, and they will be practical and effective.
In short: no flood, but a cushion.
On consumption, the article argues that demand for goods is peaking or plateauing in some categories, making services the main area for expanding demand. Supply is now being tailored to different income groups, a new approach highlighted at the July 30 meeting. On technology, it pairs the "AI+" push with a warning against rushing into things headlong in computing capacity.
On market rules, a regulation for the unified national market is confirmed for this year, and the article's call to "face up to the contradictions" signals real teeth: both a negative list and a positive list for local investment incentives, plus a standing mechanism to settle business-to-business arrears, which the article calls a chronic disease. On risks, the paths are now explicit: debt through the debt-swap package, property through high-quality urban renewal, banks through shrinking and reforming small local institutions, plus a stock-market reform to channel long-term funds in.
READ BETWEEN THE LINES
What is the Party's leadership signaling beyond the numbers? First, candor. Dong points to a detail many missed in the July 30 meeting statement: authorities must pay "great attention" to the economy's difficulties, a stronger phrase than the usual "faces." His reading: the Party sees the problems clearly and is resolved to act.
And this is the way to read China going forward. The series' central message is clear: stop fixating on quarterly or monthly figures, and focus instead on quality and structural changes. Dong adds a warning on the "K-shaped divergence" narrative, calling it overstated; the July 30 meeting statement urging "accelerating the transition between old and new growth drivers" is, in his reading, the official answer: both drivers will be managed, not one at the other's expense.
The four articles carry a message in two halves. The confident half: the 4.7-percent growth rate is the desired speed, the upgrade is real, the 15th Five-Year Plan projects starting this autumn will keep growth in a reasonable range, and "China's economy is an ocean that can weather storms." The candid half: demand is still weak relative to supply, investment is struggling, and fixing structural problems costs growth.
The summary of official messaging might be: We see the problems, we chose this path knowingly, and we have the tools to manage it. And this will produce positive spillovers beyond China's borders, as the world's largest single contributor to growth intends to keep contributing.
Thanks for reading Peking Ensight!
Subscribe for free to receive new posts and support my work.